In this guide:
 Lendzi
 Lendzi


The equity you've built in your home can do more than sit on paper. A home equity line of credit lets you tap that value for business needs like inventory, equipment, hiring, or a cash-flow gap, without selling the property or taking on a fixed lump-sum loan. But because your home secures the line, a HELOC isn't a decision to make lightly. This guide explains what a HELOC is, how it works, how to get one, and the honest pros and cons of using one to fund your business.
A home equity line of credit (HELOC) is a revolving line of credit secured by the equity in your home. You can borrow up to a set limit, repay it, and borrow again, paying interest only on what you use.
In plain terms, the home equity line of credit meaning comes down to this: your home's value, minus what you still owe on your mortgage, becomes a credit line you can draw from. For example, if your home is worth $400,000 and you owe $250,000, you have $150,000 in equity. Lenders typically let you borrow against a portion of that, not all of it.
A HELOC works more like a business credit card than a term loan. There's no single lump sum and no fixed payment schedule while you're drawing. If you don't use the line, you generally don't make payments on it.
So, how does a home equity line of credit work in practice? A HELOC has two phases, a variable interest rate, and your home as collateral.
Your home is the collateral for the line. That security is why HELOC rates are usually lower than unsecured business lines of credit. It also means that if you can't repay, the lender can foreclose. Most lenders cap your total borrowing (mortgage plus HELOC) at around 80% to 85% of your home's appraised value.
The draw period typically lasts 5 to 10 years. During this time you can borrow, repay, and borrow again up to your limit. Many HELOCs only require interest payments on the balance during the draw period, which keeps monthly costs low but doesn't reduce what you owe.
When the draw period ends, you can no longer borrow. The remaining balance is repaid, principal plus interest, over a repayment period that's often 10 to 20 years. Payments can jump noticeably at this point, so plan for it before you draw heavily.
Most HELOCs carry a variable rate tied to the prime rate, so your payment can rise or fall over time. Interest accrues on any outstanding balance, so carrying a larger balance for longer costs more. Common costs include appraisal fees, origination or closing costs, annual fees, and sometimes an early-closure fee if you close the line within the first few years. Compare these across lenders, not just the rate.
Here's how to get a home equity line of credit, from first check to first draw. A HELOC is underwritten on you and your home, not your business, so your personal finances matter most.
The pros and cons of a home equity line of credit come down to one trade-off: lower cost and more flexibility, in exchange for putting your home on the line.
The disadvantages of a home equity line of credit are real, and the first one outweighs the rest.
Both let you borrow against your home's equity; the difference is how you get the money and how you pay it back. A home equity loan gives you one lump sum at a fixed rate, while a HELOC gives you a reusable credit line, usually at a variable rate.
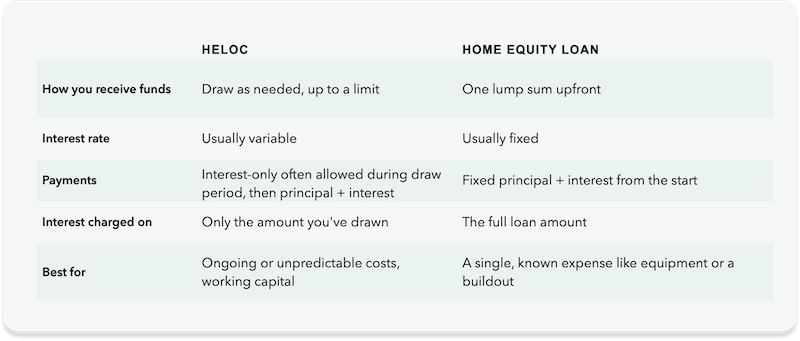
If you're not sure how much you'll need or when, a HELOC usually fits better. If you know the exact cost and want predictable payments, a home equity loan may be the simpler choice.
A HELOC can be a smart, low-cost source of capital, but only if you can comfortably carry the risk. Use this quick checklist to self-assess.
A HELOC may be a good fit if:
If you couldn’t check most of these, consider financing that doesn’t put your home at risk, such as a business line of credit, an SBA loan, or equipment financing.
Both let you borrow against your home's equity; the difference is how you get the money and how you pay it back. A home equity loan gives you one lump sum at a fixed rate, while a HELOC gives you a reusable credit line, usually at a variable rate.
A home equity line of credit (HELOC) is a revolving credit line secured by the equity in your home. You can borrow up to an approved limit, repay, and borrow again, paying interest only on the amount you use.
A HELOC has a draw period, usually 5 to 10 years, when you can borrow as needed and often make interest-only payments. After that comes a repayment period, often 10 to 20 years, when you repay principal and interest. Most HELOCs have variable rates, and your home secures the line.
Your home is the collateral for the line. That security is why HELOC rates are usually lower than unsecured business lines of credit. It also means that if you can't repay, the lender can foreclose. Most lenders cap your total borrowing (mortgage plus HELOC) at around 80% to 85% of your home's appraised value.
Your home is the collateral for the line. That security is why HELOC rates are usually lower than unsecured business lines of credit. It also means that if you can't repay, the lender can foreclose. Most lenders cap your total borrowing (mortgage plus HELOC) at around 80% to 85% of your home's appraised value.
Your home is the collateral for the line. That security is why HELOC rates are usually lower than unsecured business lines of credit. It also means that if you can't repay, the lender can foreclose. Most lenders cap your total borrowing (mortgage plus HELOC) at around 80% to 85% of your home's appraised value.
Your home is the collateral for the line. That security is why HELOC rates are usually lower than unsecured business lines of credit. It also means that if you can't repay, the lender can foreclose. Most lenders cap your total borrowing (mortgage plus HELOC) at around 80% to 85% of your home's appraised value.
Lendzi connects you with a network of 65+ lending partners, so you can compare HELOCs and business financing options side by side and choose the one that fits.