


The Fed Just Raised Rates Again: What It Means for Your Business’s Borrowing Plans
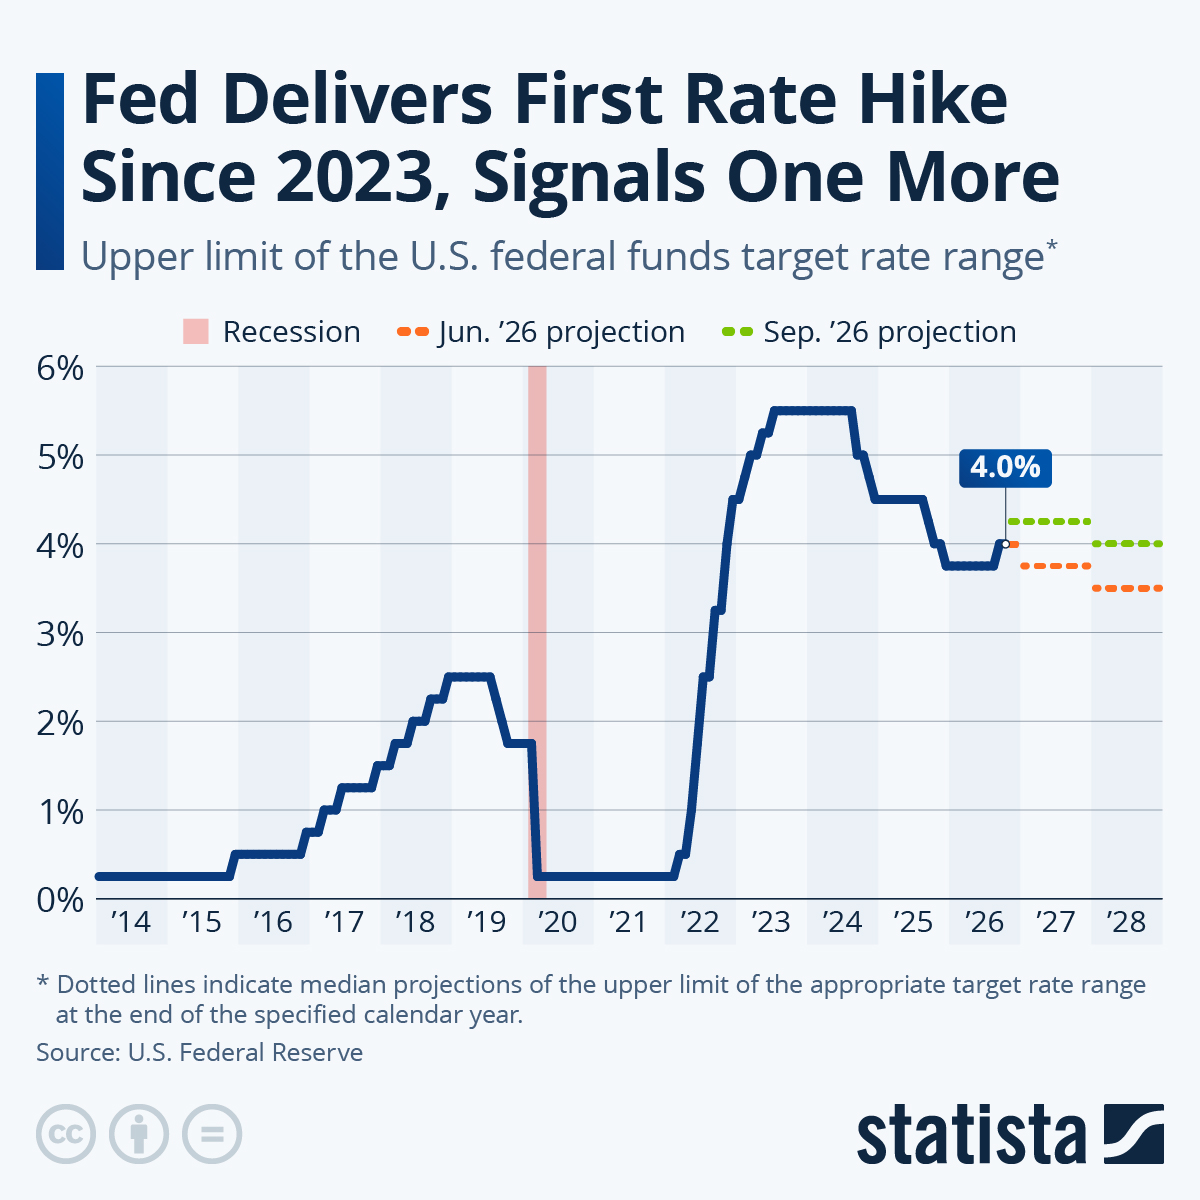
By: Orlando Abreu September 17, 2026On September 16, 2026, the Federal Reserve raised its benchmark interest rate by 25 basis points, moving the federal funds target range to 3.75%–4%. It's the first hike since 2023 after multiple rate cuts. Three rate cuts in late 2025 brought borrowing costs down, and the Fed held steady through the first half of this year. That pause is now over, and the updated projections leave the door open to another increase before year-end.
For business owners who've been waiting on the sidelines for more affordable financing options, this is the moment to pay attention, and take necessary action
What This Means for Businesses Looking to Borrow
Don’t worry. It’s not all doom and gloom. None of this means borrowing stops making sense. It does mean that the terms you lock in today matter a lot more than they did a year ago.
- Lines of credit and variable SBA loans reprice fast. Many small-business credit lines adjust monthly or quarterly, so a rate hike shows up in your payment almost immediately — unlike a large corporate bond that might be locked in for years.
- Small businesses start from a higher spread. Banks commonly price SBA 7(a) loans at prime plus 2–4.75 points, and conventional lines at prime plus 3–6 points. Because the starting point is already higher, every additional hike compounds from a bigger base.
- The math adds up quickly. A single quarter-point move can add hundreds of dollars a month to debt service on a modest loan balance. On a larger line or credit, a full percentage point of increases can mean tens of thousands of dollars a year in additional interest. This is money that comes straight out of your margin.
- New financing gets more expensive too. If you've been planning to open a new location, buy equipment, or bridge a seasonal cash flow gap, the cost of that capital is going up, not down… at least for now.
What's Happened in the Past When Rates Shift Like This?
This isn't the first time small businesses have had to navigate a change in the Fed's direction, and recent history offers a useful guide:
-
2022- 2023
WHAT HAPPENED?
The most aggressive hiking cycle in decades pushed most small business loans into double-digit rates for the first time since 2007.
WHAT WAS THE IMPACT?
The majority of small business loans had crossed into double-digit interest rates for the first time since 2007, and many owners who had financed on variable terms saw their monthly payments jump sharply within months -
2025
WHAT HAPPENED?
The 2025 cutting cycle brought some relief, with three consecutive quarter-point cuts in September, October, and December bringing the funds rate down to the 3.5%–3.75% range — the lowest level since 2022.
WHAT WAS THE IMPACT?
Businesses that had held off on financing, or that refinanced into that lower-rate window, locked in meaningfully better terms than those who waited. -
September 16th 2026
WHAT HAPPENED?
The Federal Reserve raised its benchmark rate for the first time since 2023 from 3.75% to 4%, ending a long stretch of holds and cuts.
WHAT IS THE IMPACT?
Variable-rate debt reprices fast with rate hikes showing up almost immediately for small businesses. This is where locked in rates are your best friend.
Don’t worry. It’s not all doom and gloom. None of this means borrowing stops making sense. It does mean that the terms you lock in today matter a lot more than they did a year ago.
Why Lendzi Is a Smart Choice Right Now
Here's what that means in a moments like this:
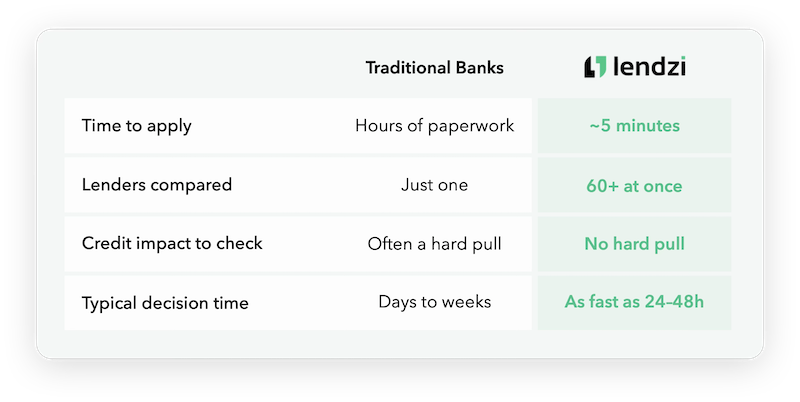
- You see multiple offers, not one bank's rate. With rates in motion, the difference between lenders can be significant. Comparing several offers side by side is the best way to find a rate that hasn't fully priced in the latest hike — or a lender still competing for your business.
- Speed protects you from further increases. A 5-minute application and decisions in as little as 24 hours means you're not waiting weeks while the rate environment keeps shifting underneath you.
- We've already navigated cycles like this one. Lendzi has funded more than $700 million to small businesses over the last 7 years across a wide range of rate environments, including the last hiking cycle.
If a rate hike is going to happen regardless, the smart move is making sure it doesn't catch your financing plans off guard.
See What’s Available to You Now.
The Fed's own projections suggest another hike could be on the table before the end of the year. If you've been considering a loan, a line of credit, or equipment financing, the window to lock in today's terms is open now, but it won't stay open indefinitely.
Submit your application with Lendzi today and compare offers from 65+ lending partners before the next rate move — it takes just 5 minutes, with decisions in as little as 24 hour
This was written for informational purposes only and does not constitute financial or lending advice. Rates and terms vary by lender and business applicant. Current figures reflect Fed policy and market data as of September 16, 2026.
About the Author

Latest Articles
Lendzi Makes Inc. Magazine’s 5000 List of the...
Making the Inc. 5000 once is a major mil...